 Explore comprehensive insights into specialized loans including gold loans, business loans, professional loans, education, agriculture, vehicle, and renovation loans in India. Discover benefits, merits, drawbacks, RBI data, and government schemes.
Let’s talk about something that often holds the key to turning dreams into reality or solving urgent crunches — specialized loans. In India’s diverse financial landscape, borrowing is no longer one-size-fits-all. Whether it’s pawning your gold for quick cash, funding a growing enterprise, upgrading your professional setup, or even supporting agriculture, lenders now offer loans tailored specifically for unique needs and segments.
In this detailed guide, we’ll dive deep into the major types of specialized loans in India along with their benefits, merits, and demerits, enriched with Indian-specific insights, real-life examples, and latest government schemes. So, buckle up, and here’s the lowdown to help you borrow smartly!
What Are Specialized Loans?
Specialized loans are designed for a particular purpose or borrower category, differing from general-purpose personal loans. They offer customized terms based on the asset pledged, the profession of the borrower, or the business activity financed. Because they cater to specific needs, these loans often come with flexibility, lower interest rates, or special eligibility criteria.
Many Indians rely on these loans for various reasons — gold loans for emergencies, Mudra loans for micro enterprises, education loans for career growth, and agricultural loans for farm productivity. The Reserve Bank of India (RBI) along with the government actively supports some of these financing products through policy initiatives and subsidy schemes to promote credit flow and economic inclusion.
 Major Types of Specialized Loans in India
-
Gold Loans: The Traditional Safety Net
India’s love for gold is legendary — not just as jewelry but also as a financial asset. Gold loans use this tradition to provide instant liquidity by pledging gold ornaments or coins.
- Interest Rate: 7% to 12% (generally lower than unsecured loans)
- Loan Tenure: 6 to 24 months
- Documentation: Minimal; ID, address proof, and the gold itself
RBI Data Insight: Outstanding gold loans doubled in one year from ₹1.16 lakh crore (May 2024) to ₹2.51 lakh crore (May 2025), driven by soaring gold prices and easier lending norms.
Benefits:
- Instant cash with quick approval (sometimes within an hour)
- No impact on credit score if repaid timely
- Higher Loan-to-Value (LTV) ratio relaxation (up to 85% for loans below ₹2.5 lakh) coming into effect April 2026
Merits:
- Ideal for emergencies like medical bills or tuition fees
- Lower interest due to collateral backing
Demerits:
- Risk of losing gold if unable to repay
- Short repayment terms can pressure some borrowers
- Penal charges for late payment can be high
Case Study: Lakshmi, a farmer from Tamil Nadu, pledged inherited gold jewelry to fund the sudden hospitalization of her father. Thanks to a gold loan, she got funds in just hours without selling precious items.
-
Business Loans: Fueling Entrepreneurial Dreams
For small businesses and startups, business loans provide vital working capital, expansion funds, or equipment purchases.
- Interest Rate: 10% to 20%, varying widely by lender and security provided
- Tenure: 1 to 10 years
- Documentation: Business registration, financial statements, tax returns
Government Support: The Pradhan Mantri Mudra Yojana (PMMY) has revolutionized access to credit for micro, small, and medium enterprises (MSMEs), providing collateral-free loans up to ₹10 lakh with digital processing in some cases.
Benefits:
- Flexible funding for diverse business needs
- Tax benefits on interest as business expense
- Schemes like CGTMSE offer credit guarantees, reducing lender risk
Merits:
- Helps maintain cash flow without dipping into personal savings
- Positive impact on growth, employment, and exports (MSMEs currently contribute 49% of India’s exports).
Demerits:
- Complex eligibility and documentation barriers for some
- Often requires collateral for higher amounts
- Fixed repayment can be challenging during lean months
Case Study: A Chennai-based startup accessed Mudra loan under ₹5 lakh with minimal paperwork, enabling purchase of machinery and doubling production capacity within a year.
-
Professional Loans: Special Perks for Professionals
Doctors, lawyers, architects, and other certified professionals get access to loans with favorable terms based on their reliable income streams and stability.
- Interest Rate: Around 9% to 15%
- Tenure: 1 to 7 years
- Documentation: Degree certificates, professional license, income proof
Benefits:
- Lower interest rates and higher loan limits
- Minimal collateral requirements for small/medium sums
- Can cover both personal and professional expenses
Merits:
- Faster approval with simple paperwork
- Higher eligible sums than generic personal loans
Demerits:
- Limited to certain professions with recognized certifications
- Income proof mandatory for each repayment cycle
- Risk of over-borrowing for lifestyle upgrades
-
Education Loans: Investing in the Future
 Education Loans: Investing in the Future
Education loans help students fund higher studies in India or abroad with benefits like moratorium period and subsidy schemes.
- Interest Rate: 8% to 12% depending on lender and collateral
- Tenure: Typically 5 to 15 years including moratorium
- Documentation: Admission proof, course fee structure, income proof
Government Schemes: The Education Loan Subsidy Scheme provides interest subsidy for families with income up to ₹4.5 lakh per annum. EMI repayment can start after course completion.
Benefits:
- Protects family savings and investments
- Tax benefits under Section 80 E of Income Tax Act
- Covers tuition, living, travel, and educational materials
Merits:
- Moratorium period avoids repayment stress during study
- Helps build credit history for students
Demerits:
- Interest burden post-study can be significant if course duration is long
- Co-borrower obligations can add pressure
Case Study: A Pune student took an education loan to pursue MBA abroad without liquidating family assets, repaying only after course completion.
Agriculture Loans: Empowering Farmers
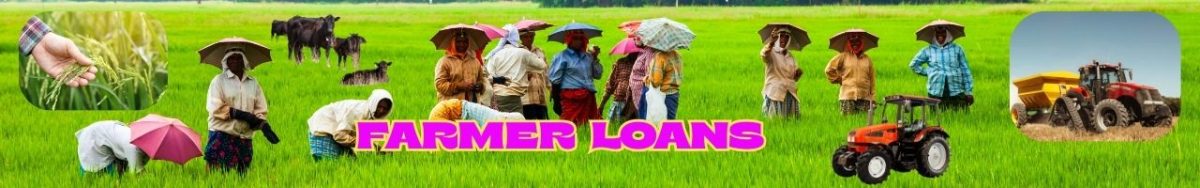
Agricultural loans support farmers with crop loans, equipment purchase, agro-infrastructure, and solar pump financing.
- Interest Rate: 4% to 11% depending on loan type and subsidies
- Tenure: Seasonal for crop loans; up to 15 years for infrastructure loans
- Documentation: Land records, crop pattern, income proof
RBI & NABARD Support: Over ₹31 lakh crore farm credit was targeted for FY 2025-26, with collateral-free loans and interest subventions for small farmers.
Benefits:
- Helps buy seeds, fertilizers, equipment, and installations
- Crop insurance available under PMFBY scheme
- Lower rates through government subsidy and Kisan Credit Card (KCC)
Merits:
- Supports rural livelihoods and improves productivity
- Reduces dependence on informal moneylenders
Demerits:
- Delays and paperwork can hamper timely credit flow
- Risk of default due to crop failure or price fluctuations
-
Vehicle Loans: For Business & Personal Mobility
 Vehicle Loans: For Business & Personal Mobility
Vehicle loans finance purchase of two-wheelers, cars, trucks, or commercial vehicles essential for business or personal use.
- Interest Rate: 9% to 16%
- Tenure: 1 to 7 years
- Documentation: Proof of income, vehicle quotation, ID
Benefits:
- Enables acquisition without upfront full payment
- Tax benefits if used for business purposes
Demerits:
- Depreciation risk if vehicle is repossessed
- Higher interest rates for used vehicles
-
Home Renovation Loans: Upgrade Your Space
Aimed at financing repairs, remodeling, or enhancements of residential or commercial properties without the need for full home loan documentation.
- Interest Rate: 10% to 16%
- Tenure: 1 to 5 years
- Documentation: Property papers, ID, income proof
Benefits:
- Minimal requirements and faster processing
- Flexible loan amount based on renovation cost
Demerits:
- Higher interest compared to standard home loans
- Shorter tenure leading to higher EMIs
Comparative Overview of Specialized Loans
| Loan Type | Interest Rate | Tenure | Collateral Needed | Key Risk |
| Gold Loan | 7%–12% | 6–24 months | Gold jewelry (pledged) | Losing pledged gold |
| Business Loan | 10%–20% | 1–10 years | May require collateral | EMI stress in low revenue |
| Professional Loan | 9%–15% | 1–7 years | Usually minimal | Limited profession categories |
| Education Loan | 8%–12% | 5–15 years (incl. moratorium) | Collateral for large loans | Loan burden post education |
| Agriculture Loan | 4%–11% | Seasonal to 15 years | Land or Kisan Credit Card | Crop failure risk |
| Vehicle Loan | 9%–16% | 1–7 years | Vehicle | Depreciation & repossession |
| Home Renovation Loan | 10%–16% | 1–5 years | Usually unsecured | Higher interest, short tenure |
Why Choose Specialized Loans?
Specialized loans are designed to match specific needs, making them often more affordable, faster to get, or easier to repay compared to generic personal loans. The trade-off is the need to meet eligibility criteria tied to your profession, assets, or loan purpose.
The Indian government and RBI continuously promote such loans, especially through schemes like Mudra (for MSMEs), PM-KISAN (for farmers), and education subsidies — boosting financial inclusion and entrepreneurship.
 FAQs on Specialized Loans
 FAQs on Specialized Loans
Generally yes, due to collateral or defined borrower profiles reducing lender risk. Yes, gold loans mainly depend on pledged gold value rather than CIBIL score. Visit bank branches or apply online with basic business documents, income proof, and Aadhaar. Yes, families with income less than ₹4.5 lakh pa may get full interest subsidy during moratorium. Yes, through Kisan Credit Cards (KCC) and various government schemes. Mostly, but some banks extend to other certified professionals like CAs and architects. The lender may auction your pledged gold to recover dues. Many lenders offer fully digital application and disbursal, especially for gold and business loans. Yes, education loans cover tuition, travel, lodging, and study materials. Typically up to 10 years, but varies by lender and business profile. Interest rates and documentation may differ; commercial loans often require additional permits and insurance. Yes, proof of property ownership is generally mandatory. Are specialized loans cheaper than personal loans
Can I get a gold loan without a credit score
How to apply for a Mudra loan
Is government subsidy available on education loans
Can farmers get collateral-free agriculture loans
Are professional loans limited to doctors and lawyers
What happens if I default on gold loan repayment
Is online application possible for all these loans
Can education loans cover living expenses abroad
What is the max tenure for business loans
How are vehicle loans different for personal vs commercial use
Do home renovation loans require property ownership proof
 Call to Action
 Call to Action
If you’re planning to borrow for any specific need — be it quick cash through a gold loan, growing a business, investing in education, or supporting farming — specialized loans provide tailored solutions. Always compare interest rates, processing times, and repayment terms before choosing. Consult trusted financial advisors to ensure you choose the best fit for your financial health. Remember, borrowing right is as critical as borrowing less! To get personalized, trustworthy guidance, contact Vishweshvarran, Insurance & Investment Consultant, phone 7658913246, website zen9zone.in.
Professional Insurance & Investment Solutions
Secure your future with expert financial guidance tailored to your life, family, or business goals.
Comprehensive Services:
Life, Health, Motor, Asset, Property & Factory Insurance
Personal & Business Loans · Credit Card Solutions · Wealth Planning & Investment Advisory
Why Choose Us?
Personalized coverage · Transparent advice · Hassle-free support · Protection that grows with your goals
Let’s build a safer, more prosperous tomorrow—together.
Call 7658913246, Email [email protected], or WhatsApp us anytime for clear, personalized financial guidance. We’re here to help you make confident, informed decisions.